Market Overview: A $147 Billion Opportunity Takes Shape
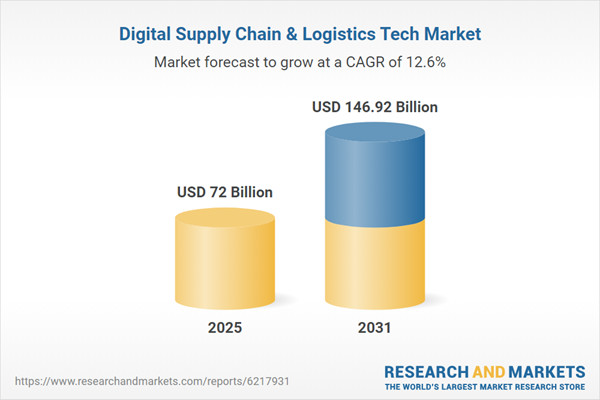
The global digital supply chain and logistics technology market is on track for a dramatic expansion over the next six years. According to a comprehensive research report published in February 2026, the market is projected to grow from $72 billion in 2025 to $146.92 billion by 2031, representing a compound annual growth rate (CAGR) of 12.62%. This growth trajectory significantly outpaces the broader technology sector, underscoring the critical role that digital transformation now plays in supply chain operations worldwide. The drivers behind this acceleration are multifaceted: the relentless expansion of e-commerce demands ever-faster fulfillment capabilities, recurring supply chain disruptions have made resilience a boardroom priority, and the maturation of artificial intelligence and automation technologies has finally made enterprise-scale deployment economically viable.
The competitive landscape features a formidable roster of global technology giants and specialized supply chain solution providers. Oracle, SAP SE, Blue Yonder, Manhattan Associates, Coupa Software, FourKites, project44, and Korber AG form the leading pack, each pursuing distinct strategies spanning technological innovation, mergers and acquisitions, and deep retail partnerships. The market is no longer confined to traditional ERP and warehouse management systems — it now encompasses AI-powered decision intelligence platforms, real-time visibility networks, digital twin simulation tools, and collaborative logistics ecosystems that connect shippers, carriers, and suppliers on shared digital infrastructure.
Regional Dynamics: North America Leads, Asia-Pacific Surges
The geographic distribution of the digital supply chain technology market reveals stark regional differences in both maturity and growth potential. North America currently commands the largest market share, with the United States alone accounting for over 80% of regional revenue. This dominance stems from the concentration of leading solution providers headquartered in the US — Oracle, Blue Yonder, Infor, Manhattan Associates, Coupa, E2open, project44, and FourKites all maintain their primary operations in North America. The region’s advanced e-commerce infrastructure, aggressive omnichannel retail strategies, and strong venture capital ecosystem have created a fertile environment for supply chain technology innovation and adoption.
The Asia-Pacific region represents the fastest-growing market globally, driven by expanding cross-border trade volumes, rising consumer expectations for faster fulfillment, and accelerating warehouse automation across manufacturing hubs. India stands out as a particularly compelling growth story — the country’s e-commerce sector achieved a gross merchandise value (GMV) of approximately $14 billion in fiscal year 2025, growing 12% year-over-year, with projections pointing toward a staggering $345 billion by 2030. This exponential e-commerce growth is creating urgent demand for AI-enabled visibility tools, IoT-based tracking systems, and smart warehouse platforms capable of handling unprecedented order volumes with precision and speed.
Europe is advancing steadily, propelled by regulatory pressures for sustainable operations and industry-wide digital collaboration initiatives. The 2025 ALSC DS Europe conference in Munich brought together over 150 automotive industry leaders to discuss AI integration, real-time visibility, and predictive logistics — a clear signal that European enterprises are moving beyond pilot projects toward full-scale digital supply chain deployments. Meanwhile, emerging markets in Latin America and the Middle East, including Brazil, Mexico, the UAE, and Saudi Arabia, are making significant investments in cloud-based supply chain platforms to modernize their logistics infrastructure.
Technology Frontiers: Robotics, AI, and the Next-Generation Warehouse
Warehouse robotics and automation represent one of the most tangible manifestations of the digital supply chain revolution. Automated storage systems, autonomous mobile robots (AMRs), robotic arms, and AI-powered warehouse orchestration platforms are fundamentally reshaping how goods are stored, picked, packed, and shipped. Amazon’s introduction of its Vulcan warehouse robot in 2025 — equipped with tactile sensing and AI-based perception — exemplifies the cutting edge of this transformation. Vulcan’s ability to handle a wider variety of products through touch-based recognition significantly accelerates picking speed while minimizing error rates, bridging the critical gap between human dexterity and automated efficiency.
Beyond hardware innovation, the software layer of supply chain technology is undergoing a paradigm shift from process automation to autonomous decision-making. FourKites launched its Loft platform in February 2026, an AI orchestration system powered by its Sophie AI engine that operates across any enterprise system — not just supply chain applications. Loft transforms real-time logistics visibility data into enterprise-wide intelligent decision support, representing the evolution from supply chain visibility platforms to full-scope AI orchestration platforms. Similarly, project44 recently appointed Birju Shah, a former Uber AI executive, as Senior Advisor to accelerate the application of agentic and reasoning AI across its Movement platform, signaling the industry’s pivot toward autonomous supply chain intelligence.
Collaborative Logistics: Breaking Down Information Silos
The rise of collaborative logistics networks represents perhaps the most strategically significant trend in the digital supply chain landscape for 2026. Traditional supply chain management has long suffered from severe information fragmentation — shippers, carriers, suppliers, and third-party logistics providers each operate with incomplete visibility into the broader network, leading to suboptimal decisions, excessive safety stock, and sluggish response times. New collaborative platforms are dismantling these information silos by connecting all stakeholders on unified digital infrastructure with shared data visibility and coordinated planning capabilities.
Bosch’s launch of its Supply Chain Studio in India in 2025 provides a compelling blueprint for this collaborative model. The cloud-based platform integrates data from suppliers, transport providers, and warehouses, enabling all participants to share real-time visibility and engage in joint planning. The value proposition extends well beyond improved transparency — by enabling all supply chain participants to optimize collectively rather than individually, collaborative networks can significantly reduce inventory redundancy, minimize transportation deadhead miles, and enhance customer service levels. Industry analysts predict that collaborative logistics platforms will represent one of the fastest-growing investment categories within the digital supply chain space over the next five years.
Software Dominance: The Platform Economy Takes Hold
Within the component breakdown of the digital supply chain technology market, the software segment captured approximately 47% of total market share in 2025, establishing itself as the largest single category. This figure reflects a fundamental industry shift from hardware-centric to software-defined supply chain operations. Modern supply chain management increasingly depends on highly integrated software platforms that connect and optimize every stage of the value chain — from procurement and production planning through warehousing and last-mile delivery. The platform model is winning because it offers scalability, rapid deployment through cloud architectures, and continuous improvement through AI and machine learning capabilities.
The adidas-project44 partnership illustrates the evolving dynamics of enterprise supply chain software selection. Project44 CEO Jett McCandless revealed that closing adidas as a customer took eight years of persistent engagement. The adidas team needed to simultaneously manage the immediate high-stakes pressure of an approaching World Cup while evaluating how software and AI would transform their supply chain over the next decade. This case study highlights two critical market trends: first, major enterprises are taking increasingly deliberate, multi-year approaches to selecting supply chain technology partners; second, the expectation for supply chain software has elevated from tactical tooling to strategic platform infrastructure that must demonstrate long-term technological evolution capability and deep industry domain expertise.
Looking Ahead: The Next Inflection Points for Digital Supply Chains
As the market progresses toward its projected $147 billion valuation by 2031, several critical inflection points will shape the trajectory of digital supply chain technology. Agentic AI — autonomous artificial intelligence agents capable of perceiving environmental changes, formulating response strategies, and executing actions within predefined governance frameworks — is poised to fundamentally alter how supply chains operate. Both FourKites’ Loft platform and project44’s Movement platform are evolving in this direction, and industry observers expect a significant increase in enterprise deployments of autonomous AI agents for specific supply chain use cases within the next two to three years.
Equally important is the shifting value proposition of supply chain digitization from pure efficiency optimization toward resilience building. The cumulative impact of the COVID-19 pandemic, geopolitical conflicts, and increasingly frequent extreme weather events has made it clear that hyper-efficient but rigid supply chains are dangerously vulnerable to black swan disruptions. Platforms that offer real-time risk sensing, multi-scenario simulation, and rapid replanning capabilities are attracting disproportionate investment. The market’s growth from $72 billion to $147 billion fundamentally reflects a global enterprise transition from digital experimentation to deep digital commitment — and within this transformation, platform companies that deliver end-to-end visibility, AI-driven decision intelligence, and ecosystem collaboration capabilities will emerge as the defining winners of the next six years.
Source: GlobeNewsWire