A potential blockade of the Bab el-Mandeb Strait threatens to raise Brazilian fertilizer import costs by up to 20%, disrupt Black Sea grain exports to Asia, and inflate diesel and freight expenses. Saudi Arabia — a key supplier of phosphate fertilizers and sulfur to Brazil — faces severe export constraints if both Red Sea and Hormuz routes are compromised. Analysts warn DAP prices could surge ahead of India’s major procurement auction, while wheat and corn shipping premiums may rise 15–25%. Brazil’s heavy reliance on imported fertilizers (85%+) and road transport magnifies domestic exposure.
According to www.cnnbrasil.com.br, a potential blockade of the Bab el-Mandeb Strait — a critical maritime chokepoint between Yemen and Djibuti — threatens to raise Brazilian agricultural production costs, with fertilizer import prices potentially surging by 20% amid disrupted logistics, elevated freight rates, and higher diesel costs.
Fertilizer Supply Chain at Risk
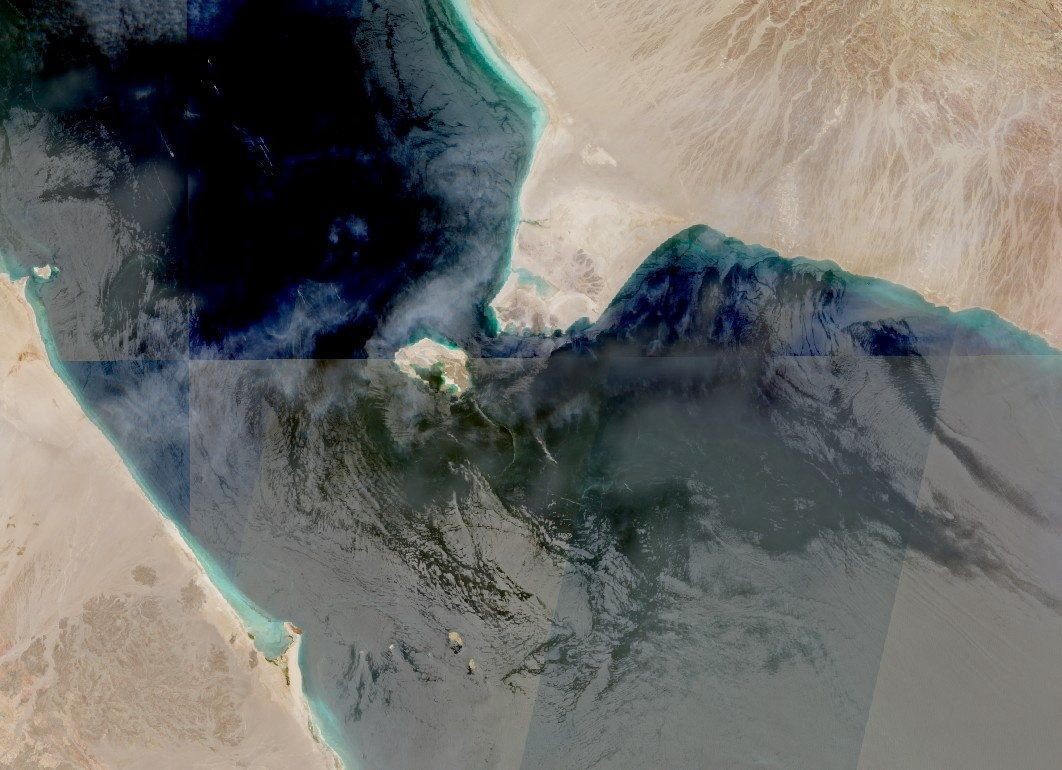
The Bab el-Mandeb Strait connects the Indian Ocean to the Red Sea and Suez Canal, forming a strategic corridor for global trade. According to Jackson Campos, an international trade specialist, the strait handles substantial volumes of urea, ammonia, phosphate fertilizers, natural gas, petroleum, diesel, aviation fuel, wheat, and rice. He emphasized that
“The chains requiring the most attention are urea, ammonia, phosphate fertilizers, natural gas, petroleum, diesel, aviation fuel, wheat, and rice. Urea and ammonia are especially sensitive because they depend on natural gas and have significant production in the Middle East.” — Jackson Campos, international trade specialist
Brazil imports the majority of its fertilizers — over 85% by volume — and relies heavily on Middle Eastern suppliers, particularly Saudi Arabia, a leading global exporter of phosphate fertilizers and sulfur. With the 2026/27 soybean planting season approaching, international procurement is already underway. As Tomás Pernías, inputs analyst at StoneX, noted, Saudi producers have increasingly relied on Red Sea ports as alternatives to the Strait of Hormuz, but land transport across Saudi territory to those ports adds cost and complexity. A full disruption of both the Red Sea and Hormuz routes would severely constrain Saudi fertilizer exports.
Global Phosphate Markets Tighten
Renata Cardarelli, agriculture and fertilizers pricing lead at Argus, warned that the current global phosphate supply is already tight, heightening vulnerability to logistical shocks. She highlighted the DAP (diammonium phosphate) market as especially exposed:
“The measure places at risk especially DAP exports to South Asia at this time — a period of globally tight supply and on the eve of a likely major DAP procurement auction in India.” — Renata Cardarelli, agriculture and fertilizers pricing lead, Argus
If Saudi DAP shipments are forced to bypass Bab el-Mandeb, vessels would need to transit the Suez Canal and circumnavigate Africa — adding 10–14 days to voyage times to Asian markets. This detour also increases overland transport costs through the desert to Red Sea ports, further inflating final delivered prices. Cardarelli stressed that while the exact enforcement mechanism remains unclear — the Houthis have not specified whether restrictions apply only to Saudi-flagged vessels or to all ships calling at Saudi Red Sea ports like Yanbu — any sustained interruption would directly feed into upward price pressure worldwide, including in Brazil.
Grains and Bulk Logistics Under Pressure
Beyond fertilizers, bulk agricultural commodities face mounting logistical risk. Campos identified wheat, rice, and portions of corn flows as especially vulnerable due to their high-volume, low-value-per-tonne profile and heavy dependence on maritime routing. Ana Luiza Lodi, grains analyst at StoneX, confirmed that significant volumes of bulk grain — particularly wheat from the Black Sea region — transit Bab el-Mandeb en route to Asia, the Middle East, Africa, and Europe. The Black Sea’s importance is underscored by Russia’s status as the world’s top wheat exporter and Ukraine’s role as a major corn supplier.
Lodi noted that the grain market is already operating under heightened risk awareness following the escalation of the Russia-Ukraine war. A new maritime blockade in the Red Sea region would further elevate insurance premiums, freight rates, and overall logistics complexity. According to her analysis, such disruptions could lift risk premiums by 15–25% for affected routes — compounding existing pressures from the ongoing instability in the Strait of Hormuz.
Domestic Impact and Market Response
For Brazil, the primary transmission channel is cost inflation: higher global fertilizer prices, elevated diesel costs (which directly power farm machinery and road transport), and increased freight expenses for imported inputs and exported grains. Campos stated plainly:
“The biggest risk for Brazil lies in rising production costs, given the country imports most of the fertilizers it uses and depends heavily on road transport to move its harvest.” — Jackson Campos, international trade specialist
While international price spikes typically pass through to domestic markets, Cardarelli cautioned that Brazilian importers may resist accepting steep increases — creating negotiation friction and potential delays in input acquisition ahead of planting. That resistance, however, cannot fully insulate the sector from systemic cost pressures originating in a chokepoint handling 12% of global seaborne trade, according to industry estimates cited by multiple analysts in the source material. The convergence of Red Sea volatility, Black Sea uncertainty, and Hormuz constraints creates a uniquely fragile moment for globally integrated agri-logistics.
Source: cnnbrasil.com.br
Compiled from international media by the SCI.AI editorial team.