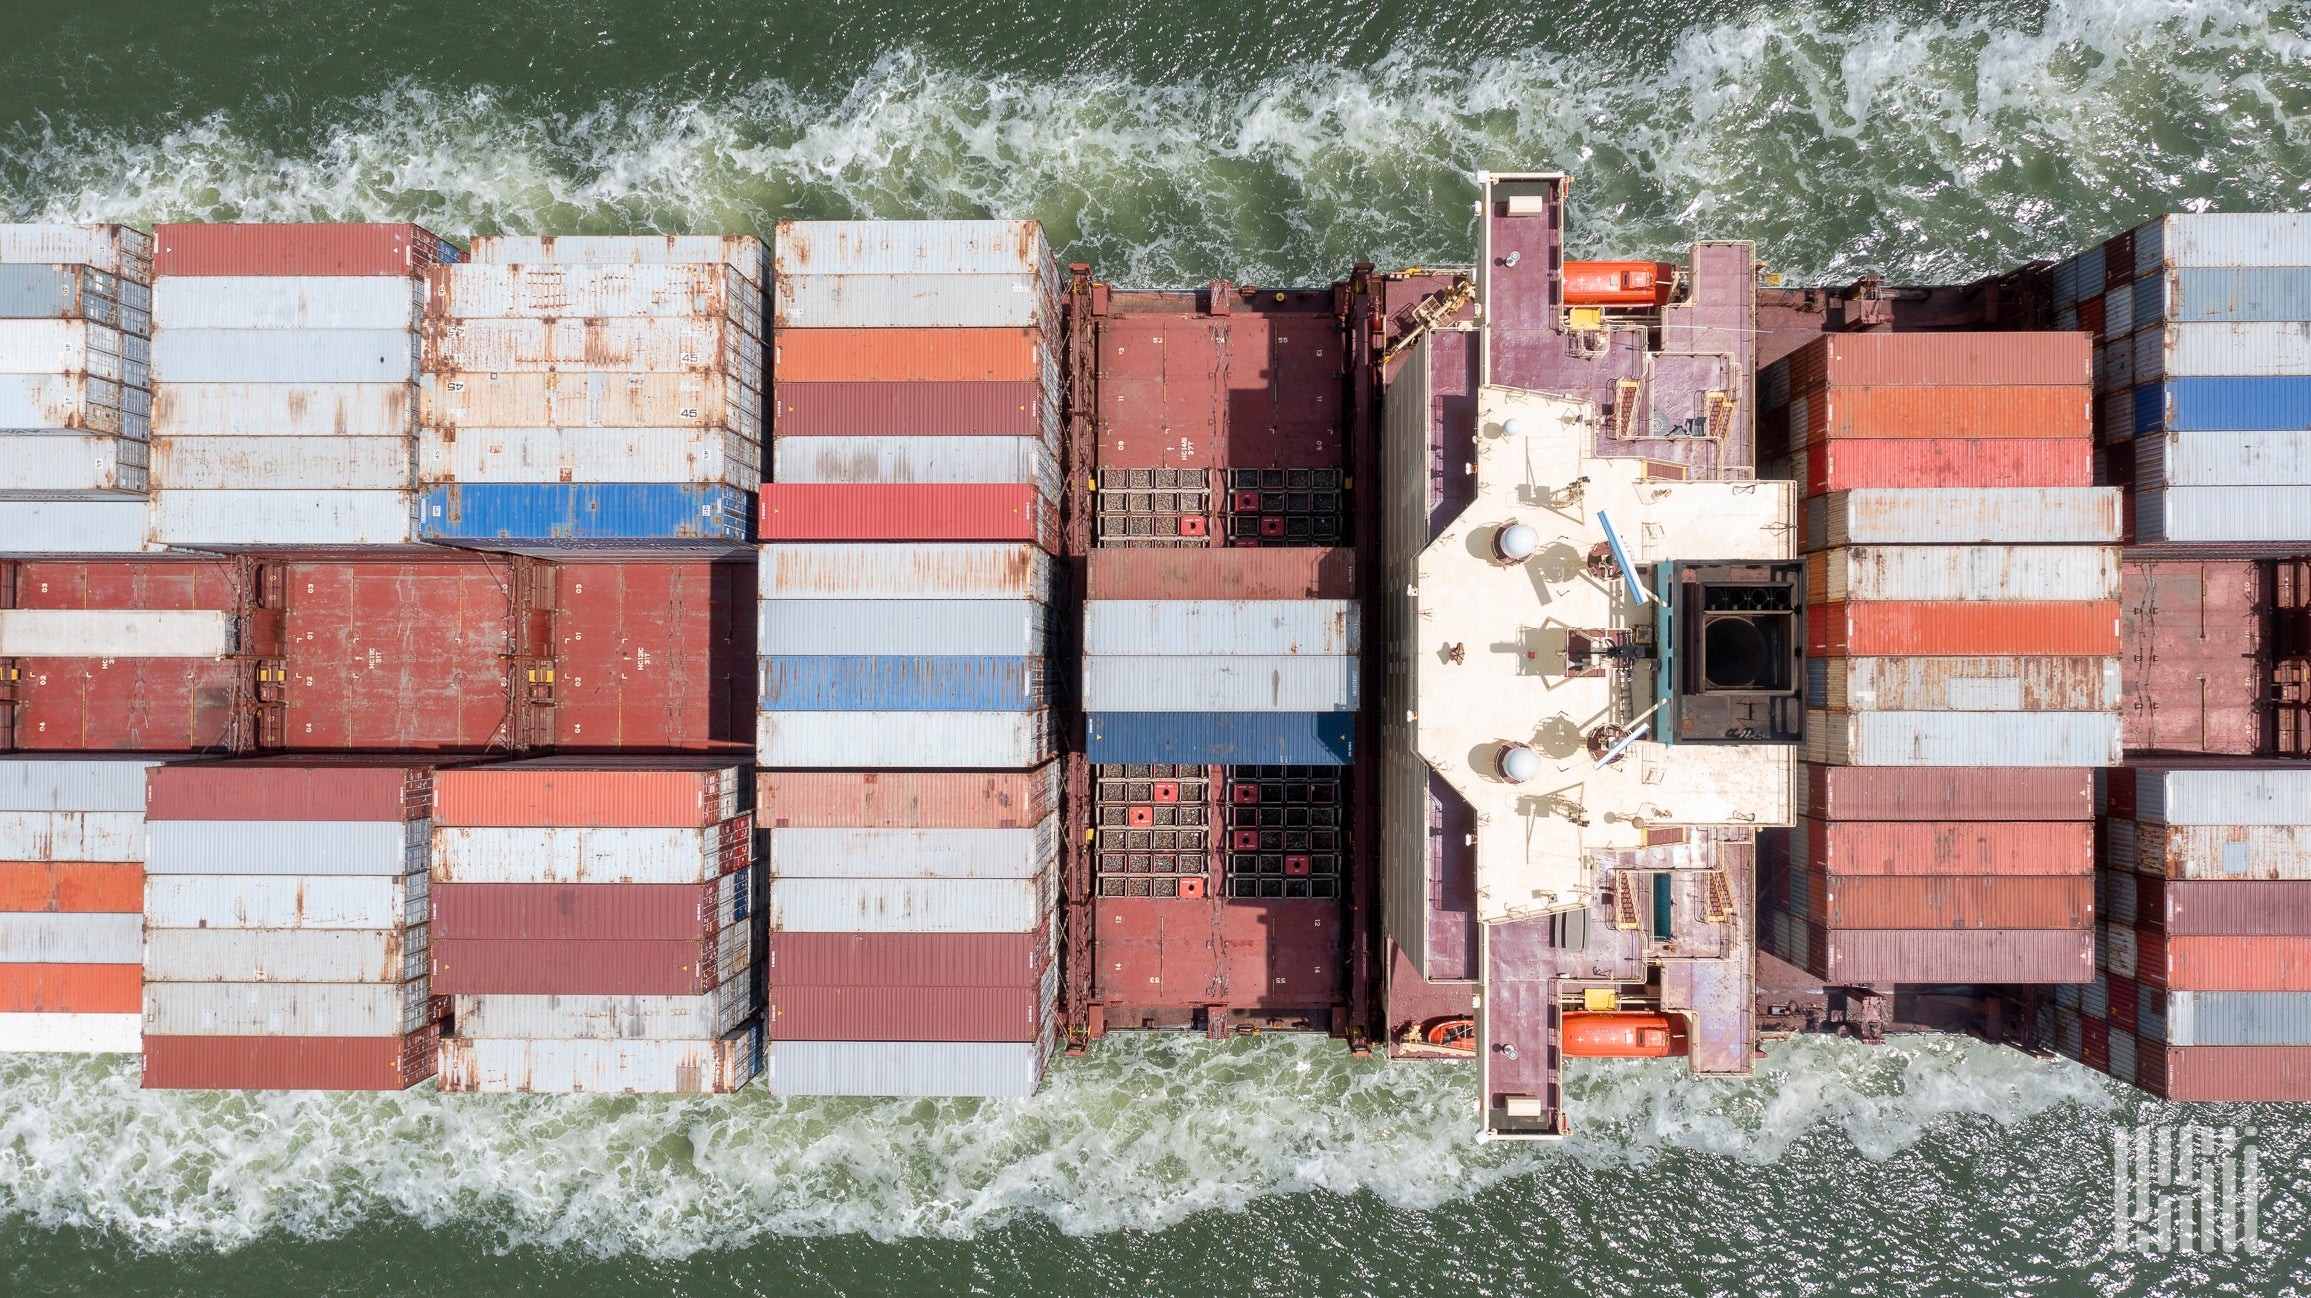
Global container volumes hit 17.35 million TEUs in September 2026, up 8% year on year, while North American imports climbed 9%, according to Container Trade Statistics data reported by FreightWaves. Third-quarter volumes reached 52.2 million TEUs, up 2.4% from the second quarter. The Global Price Index rose to 123 points in September, 5.1% higher than August and 62% above September 2025, as route disruption, Panama Canal constraints and port congestion kept pricing pressure on carriers even as cargo demand held firm.
Global container volumes reached 17.35 million TEUs in September 2026, up 8% year on year, even as the Global Price Index climbed to 123 points, according to FreightWaves citing Container Trade Statistics (CTS) data. The divergence between resilient cargo demand and rising freight prices defined the third quarter.
Volumes hold near record levels
September liftings slipped 1.4% from August, but that decline followed the highest monthly volume ever recorded in the CTS database. Year-to-date volumes remained 5% above the same period in 2025, sustaining the growth rate seen since June.
Third-quarter global volumes totaled 52.2 million TEUs, an increase of 2.4% from the second quarter. The gains came as the industry continued to face geopolitical disruption, capacity constraints and higher operating costs.
Every region recorded higher imports in the third quarter than in the same period of 2025, according to CTS, suggesting broad-based demand rather than growth concentrated in a single trade lane.
North America leads import growth
North American imports increased 9% year on year, driven primarily by cargo originating in Asia and Europe. That marked an acceleration from the 7% annual growth recorded in the second quarter, extending the region’s recovery following weaker performance earlier in the year.
The acceleration stands out because North America was one of only two regions to post a year-on-year decline in exports during the third quarter, with outbound volumes falling 1%. The imbalance points to continued strength in inbound consumer and industrial cargo.
The Indian sub-continent/Middle East also returned to quarterly year-on-year import growth following disruption earlier in 2026. Although the increase amounted to only about 6,600 TEUs, it represented an improvement from the second quarter, when imports fell 12%.
Freight pricing pressure intensifies
The Global Price Index rose to 123 points in September, up 5.1% from August and 62% above its September 2025 level. The increase pointed to pressure on container shipping even as cargo volumes continued to expand.
Disruption to major shipping routes, constrained capacity and higher operating costs continued to influence pricing. The ongoing Persian Gulf crisis, constraints surrounding the Panama Canal and pressure on shipping capacity added to the difficult operating environment.
Port congestion and high terminal utilization also threatened to limit the industry’s ability to clear backlogs and keep cargo moving efficiently, CTS said. Those operational bottlenecks compound the cost pressure already visible in the price index.
Export performance diverges by region
Export performance was less uniform than imports. The Indian sub-continent/MidEast and North America were the only regions to record year-on-year declines in the third quarter, with volumes falling 7% and 1%, respectively.
Asia and Sub-Saharan Africa posted the strongest percentage growth, each recording an 8% increase. Strong cargo flows between the two regions contributed to their respective gains.
European exports rose 3% from the third quarter of 2025, supported by increased shipments to most destination regions. However, the gap between the region’s inbound and outbound trade persisted: Europe imported approximately 1.5 containers for every container exported over the year to date.
Source: FreightWaves
Compiled from international media by the SCI.AI editorial team.