Skip to content

Manufacturing

Analysis

Apple’s iPhone Duo assembly yield at 60%, October 23 launch at risk

Apple’s first foldable iPhone, the iPhone Duo, faces a critical production hurdle with final assembly yields stuck at just 60% one month before its October 23 launch. Foxconn’s yield remains below threshold, prompting Apple to consider relaxing quality standards. Global inventory targets are set at 6–8 million units — sharply below typical Pro models’ 20–30 million. Counterpoint forecasts 6 million units shipped in 2026, capturing 25% of the global foldable market. Key components from Samsung Display and Chinese suppliers like Lens Technology and Lingyi iTech continue to face yield and timing challenges.

Original source: Source information pending

Apple’s iPhone Duo assembly yield at 60%, October 23 launch at risk

According to finance.biggo.com, Apple’s first foldable smartphone, the iPhone Duo, is facing a critical production bottleneck just one month before its scheduled retail launch on October 23, with final assembly yields hovering at only 60%.

Production Yield and Quality Standards

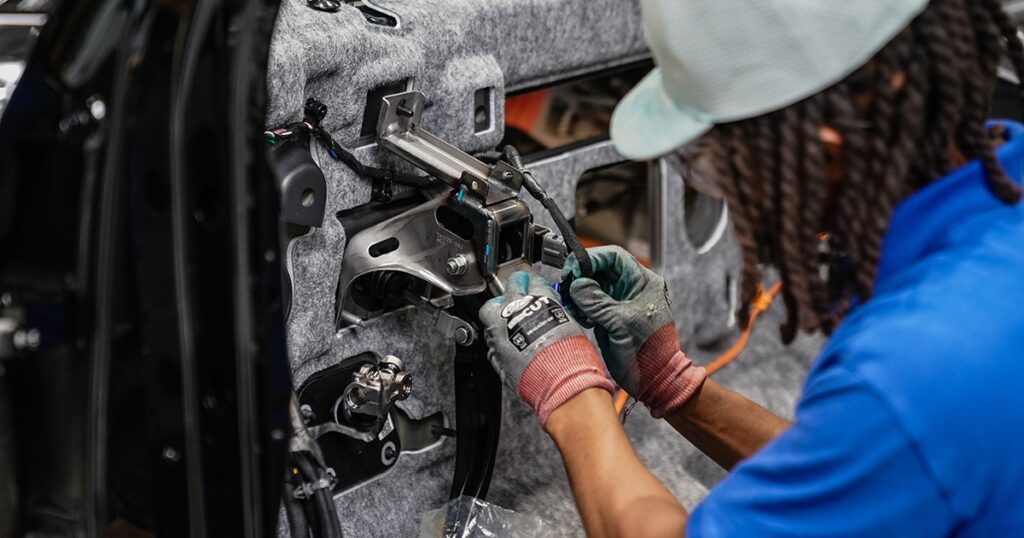
Foxconn’s current final assembly yield for the iPhone Duo stands at just above 60%, according to an exclusive report by Jiemian News. Under Apple’s existing quality standards, reaching mature yield levels could take another six months to a year. A source close to Foxconn’s supply chain confirmed suppliers are awaiting Apple’s decision on whether to relax those standards — a move that would accelerate mass production. The source emphasized that the low yield stems not from a single unresolved technical flaw, but from Apple’s inexperience in mass-producing foldables: production lines require iterative fine-tuning of equipment, processes, and parameters during actual operation.

The hinge specifications and screen crease issues have weighed on the timeline, as noted in a September 3 research report by Mizuho Securities. Meanwhile, OLED panels supplied by Samsung Display and hinge-related components have also experienced insufficient yields, delayed deliveries, and design adjustments — compressing downstream debugging time.

Sales Targets and Market Position

Apple’s global inventory target for the iPhone Duo this year is approximately 6 to 8 million units, far below the 20 to 30 million units typically shipped for a mainstream Pro or Pro Max model per cycle. Retail channel sources indicate Apple has provided sales guidance exceeding 5 million units, while Counterpoint Research estimates shipments in 2026 will be capped at around 6 million units, capturing roughly 25% of the global foldable market share at launch.

The device opens for pre-orders on October 16 — 36 days after its unveiling on September 10 by newly appointed CEO John Ternus. That interval stretches nearly a month longer than Apple’s five-year average of about three days from unveiling to pre-order.

Technical Challenges and Supply Chain Integration

The crease issue — though less visible than on most competing foldables — remains short of Apple’s original vision of perfection. Apple has broken the problem into three interdependent challenges: screen material behavior, light reflection control, and folding trajectory precision. Solutions include a specialized adhesive layer to release bending stress, nano-texturing to disperse reflected light, and a hinge-and-support structure to hold the display flat when unfolded.

China’s Lens Technology exclusively developed the custom nano-textured ultra-thin glass (UTG) used in the inner display. The company also supplies CPI film, UTG support plates, and 3D glass cover plates for Apple’s foldable project. Lingyi iTech, another Chinese supplier, provides hinge precision structural components, screen support plates, ultra-thin VC vapor chambers, and flanged ultra-thin stainless steel battery enclosures.

Source: finance.biggo.com

Compiled from international media by the SCI.AI editorial team.
Ask SCI.AI Finished reading? Continue with SCI.AI. Explore the related policy, route, company and historical context. Continue asking
Transpacific Rates Near Covid Peaks as Carriers Add Capacity
Manufacturing

Transpacific Rates Near Covid Peaks as Carriers Add Capacity

Container shipping spot rates from the Far East to the US west and east coasts have surged by 324% and 325% since 28 February, reaching $7,960 and $11,259 per FEU on 17 September — just 17.9% and 11.2% below their 2022 pandemic peaks. Carriers have raised offered capacity by 6–7% month-on-month, while vessel utilisation now sits at 85–90% in 2026, eight points above pre-pandemic norms. Fleet orderbooks stand at 35% (Maersk), 39% (MSC, CMA CGM), and 52% (COSCO) of current fleets, signaling potential pressure on future rates.

SEMICON India 2026 Inks 25 Partnerships Across Chip Supply Chain
Manufacturing

SEMICON India 2026 Inks 25 Partnerships Across Chip Supply Chain

SEMICON India 2026’s second day featured 25 cross-sector partnerships, including Tata Electronics’ collaborations with INOX Air Products and Sumitomo Chemical to localise high-purity gases and wet chemicals. L&T Semiconductor Technologies announced four product-development alliances focused on silicon carbide modules and smart-meter IoT solutions. A government-backed pilot for indigenous silicon carbide power modules will launch at POWERGRID’s 1,000 MW Pusauli project in Bihar. The India Deep Tech Alliance disclosed $263 million invested across 56 deep-tech firms, while the India Semiconductor Academy—backed by Cadence, Micron, Synopsys, and IIT Kanpur—was unveiled as an industry-led skilling platform.

U.S. Factory Output Falls 0.3% in August, First Drop This Year
Manufacturing

U.S. Factory Output Falls 0.3% in August, First Drop This Year

U.S. factory output fell 0.3% in August — its first decline this year — according to Federal Reserve data released September 18, 2026. Business equipment output dropped 0.5%, auto production fell 1.2%, and factory capacity utilization slid to a five-month low of 75.7%. Total industrial production was unchanged, with utility output rising 1.8% and mining edging up. The cooling reflects higher input costs and supply-chain disruptions tied to wars in the Middle East and Ukraine. Though August marked a pause, business equipment and defense/space output remain above year-ago levels.

Welcome Back!

Login to your account below

Create New Account!

Fill the forms below to register

Retrieve your password

Please enter your username or email address to reset your password.

Scan to share via WeChat

Open WeChat and scan the QR code to share

QR Code

Add New Playlist