Asia's air cargo export market is splitting into two speeds ahead of peak season: AI hardware demand is lifting transpacific flows, while new EU import rules are depressing Asia–Europe volumes. Taiwan's July export orders hit $97.94bn — up 61.9% YoY — driven by 88.9% growth in US-bound orders and 89.5% growth in ICT products. China/Hong Kong–US air cargo rose 13% YoY in August, versus a 14% decline to Europe. Fuel surcharges climbed sharply, with Cathay Pacific's HK-based charge rising to HK$11.20/kg. Carriers including Afcom Holdings and Ethiopian Airlines are expanding freighter fleets, while FedEx and DHL reintroduce older aircraft types.
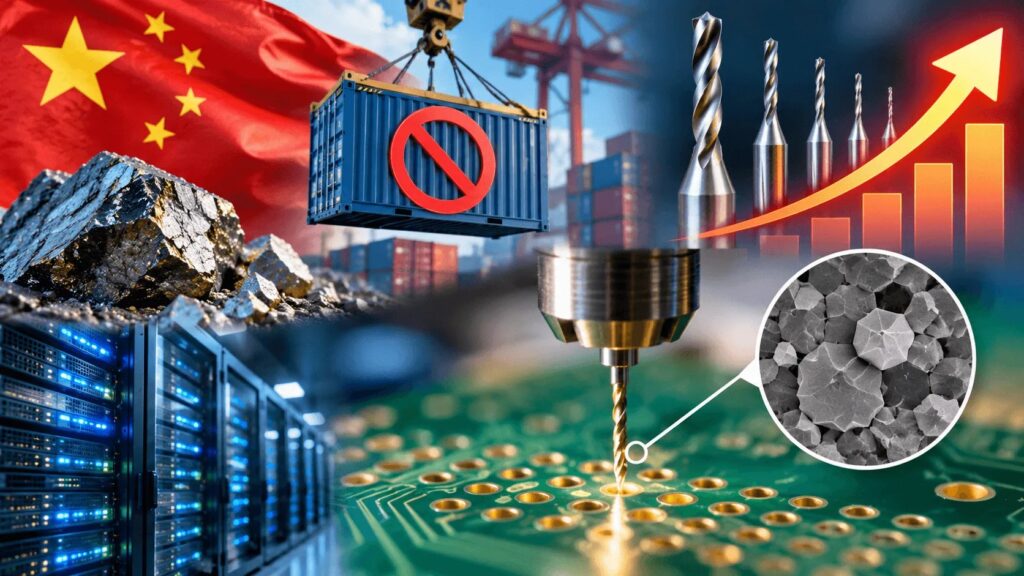
According to The Loadstar, Asia’s air cargo export market is entering peak season with starkly divergent performance: robust AI hardware demand is driving transpacific volumes upward, while new EU import rules are suppressing Asia–Europe flows.
AI-Driven Export Surge in Taiwan
Taiwan’s export orders hit a monthly record of $97.94bn in July 2026, surging 61.9% year on year. Orders from the US alone jumped 88.9%, reaching $40.79bn — the largest monthly increase on record. Information and communications technology product orders rose 89.5%, with server and cooling-system demand exceeding expectations, according to Taiwan’s Ministry of Economic Affairs.
Actual exports followed closely: July shipments totaled $75.3bn, up 32.9% year on year. Electronic components rose 50.5%, and integrated circuits surged 52.3%. This tech-driven expansion is directly translating into airfreight demand, as time-sensitive data-center construction schedules require rapid movement of high-value hardware.
Divergent Transpacific and Asia–Europe Trajectories
WorldACD data shows combined China and Hong Kong air cargo volumes to the US rose 13% year on year in August, while volumes to Europe fell 14%. Hong Kong–Europe tonnage declined 30% year on year and was 24% below its June level — a drop linked to the EU’s 1 July termination of its €150 de minimis duty exemption and introduction of a €3 charge on low-value imports.
Spot rate differentials reflect this split: China/Hong Kong–Europe rates fell from $5.22 per kg in May–June to $4.34 in August — a 17% decline. Their year-on-year premium narrowed from 32% in May to just 11% in August. By contrast, China/Hong Kong–US rates dipped from $6.59 to $5.89 per kg (11% drop), yet remained 26% above last year’s level.
Fuel Surcharges Climb Amid Jet Fuel Price Spikes
Cathay Pacific’s long-haul cargo fuel surcharge from Hong Kong rose from HK$6.70 per kg in late July to HK$10.10 in early August, then to HK$10.60, and finally to HK$11.20 for the first half of September. This surge tracks sharp increases in jet fuel prices, which rose 8.2% during August and were 74.2% higher year on year by 28 August, according to the TAC Index.
Capacity Expansion Underway Across Carriers
Afcom Holdings, an Indian cargo operator, has issued a letter of intent for up to four Boeing 777-8F freighters — a major step beyond its current fleet of 737-800 freighters. Meanwhile, Ethiopian Airlines is finalising an order for as many as ten 777 freighters, including two 777-200Fs and eight 777-8Fs; it already operates 12 -200Fs and has agreed to lease two converted 777-300ERSFs from AerCap for delivery in 2028.
More immediate capacity is returning: MD-11Fs are re-entering service at FedEx and Western Global Airlines, and the first Mammoth Freighters 777-200LRMF conversion has been delivered for operation by DHL. The latest Freightos Air Index shows China–North America rates rose 5% last week to $6.30 per kg, while China–North Europe rates increased 6% to $4.88 per kg.
Source: The Loadstar
Compiled from international media by the SCI.AI editorial team.