According to gapki.id, the rapid proliferation of 442 palm oil mills without plantations — known as non-conventional PKS — is undermining Indonesia’s mature palm oil supply chain, with reported 60% theft rates of fresh fruit bunches (TBS) in some plantations and growing risks to traceability, sustainability compliance, and market fairness.
Threats to Integrated Supply Chain Stability
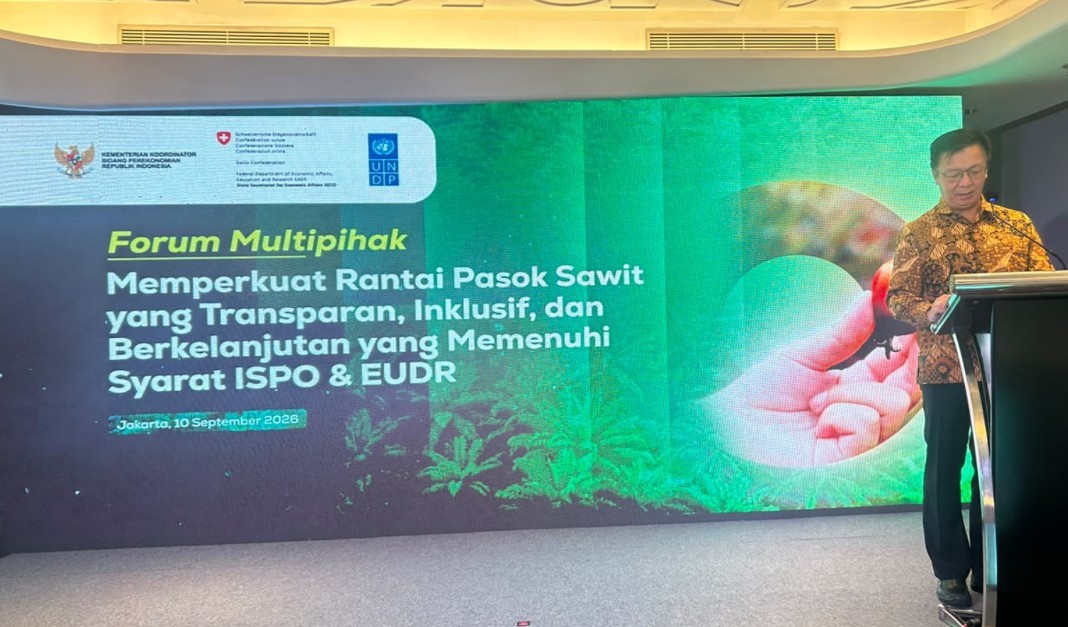
At the United Nations Development Programme’s (UNDP) multi-stakeholder forum held on 10 September 2026 in South Jakarta, GAPKI highlighted how non-plantation mills and informal collection points (“berondolan”) disrupt a supply ecosystem that is otherwise highly integrated — supported by breeding research, domestic and export logistics infrastructure, and significant private investment. According to Agam Fatchurrochman, GAPKI’s Head of Sustainability, these entities distort long-term supply contracts with smallholders and fuel unhealthy competition for raw materials.
He stressed that the issue cannot be resolved unilaterally: “This problem cannot be handled individually by companies; it requires a joint monitoring system implemented by all stakeholders.” The forum brought together Indonesia’s Coordinating Ministry for Economic Affairs, relevant ministries and agencies, smallholder associations, international development partners, academics, and civil society organizations.
GAPKI was represented by Deputy Chairperson II Susanto, standing in for Chairperson Eddy Martono, who was unable to attend. The event took place at JS Luwansa Hotel in South Jakarta.
Rising Theft, Conflict, and Regulatory Gaps
Agam cited member reports indicating TBS theft rates reaching 50–60% across several estates — driven by intergenerational informal harvesting practices and increasingly organized theft rings willing to confront security personnel. He also flagged the emergence of unauthorized loading ramps (“loading ramp liar”), which convert formerly secure plantation zones into conflict-prone areas and are suspected of acting as receivers for stolen fruit.
A core challenge, he noted, is the unequal regulatory burden: conventional mills undergo routine environmental impact assessments (AMDAL), licensing checks, and metrology oversight, while non-conventional units face minimal scrutiny on legality, waste management, environmental compliance, or trade standards. As a result, the cost of compliance for conventional mills and farmers — including High Conservation Value/High Carbon Stock (HCV-HCS) standards — remains disproportionately high.
This imbalance directly affects national crude palm oil (CPO) quality: TBS from berondolan typically exhibits higher free fatty acid (FFA) content and inconsistent quality, lowering mill yields, increasing refining costs, and reducing downstream efficiency.
Reputational Risk Amid Global Traceability Mandates
With Indonesia producing 61% of global CPO, Agam warned that non-compliant mills jeopardize the country’s sustainability reputation under tightening international frameworks — especially the EU Deforestation Regulation (EUDR), which takes full effect on 30 December 2026, and existing standards like RSPO and ISPO. He questioned whether non-conventional mills adhere to No Deforestation, No Peat, No Exploitation (NDPE) principles or meet tier-3 traceability requirements — i.e., full supply chain visibility down to individual smallholder plots.
“If non-conventional mills fail to meet these standards, it risks tarnishing Indonesia’s overall sustainable palm oil reputation and opens pathways for opaque, untraceable supply chains,” he said.
Structural Challenges Facing Independent Smallholders
Researcher Ratnawati Nurkhoiry from the Palm Oil Research Center (PPKS) added that independent smallholders — who manage 69% of Indonesia’s 16.8 million hectares of smallholder plantations, or ~4.7 million hectares — remain trapped in a “vicious cycle”: low productivity leads to low income, reinforcing dependence on intermediaries and incentivizing risky land expansion. She noted that loading ramps emerged partly to address structural gaps: volume consolidation, payment speed, and market access.
However, each additional link — farmer → loading ramp → agent → mill — shrinks the farmer’s share of final TBS value. Her data confirmed 442 non-plantation mills operating nationwide, noting their dual impact: while intensifying unfair supply competition and eroding legal and quality standards, they also expand market access and offer more competitive pricing for smallholders.
A PPKS pilot in North Sumatra demonstrated improvement potential: converting a commercial loading ramp into an RSPO-certified cooperative for independent smallholders lifted productivity, increased income, and cut production risk by 55% versus non-certified peers.
Regulation Over Elimination: A Shared Governance Approach
M. Windrawan Inatha, Strategic Advisor at CECT Trisakti University and former RSPO advisor, emphasized that loading ramps fulfill vital economic and social roles — including providing informal financing such as fast-track loans inaccessible through formal financial institutions. “Loading ramps must be regulated, not eliminated,” he stated.
GAPKI supports inclusive smallholder participation and freedom of enterprise but rejects permissiveness toward untraceable, quality-compromising, theft-enabling, or conflict-generating operations. Its proposed solutions include harmonized compliance rules (e.g., mandatory AMDAL, UKL-UPL, SIMPEL, PROPER), cross-agency enforcement (police, environmental agencies, industry and trade departments), consistent ISPO certification, exporter collaboration on tier-3 mapping, and enhanced capacity building for independent suppliers near plantations.
Source: gapki.id
Compiled from international media by the SCI.AI editorial team.