U.S. containerized imports rose 3.8% from July to 2.60 million TEUs in August, supported by higher volumes at major East, Gulf and West Coast ports and broad gains across sourcing countries.
Record-high volume amid mounting trade risks
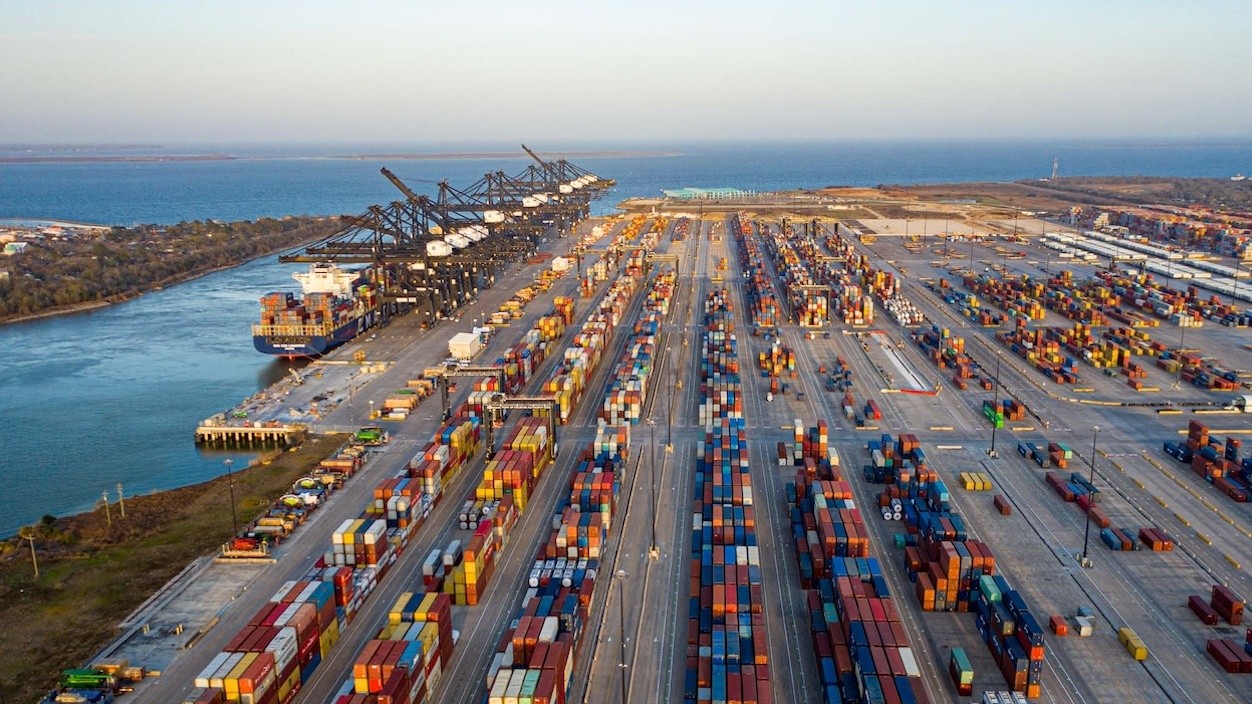
Import volume reached 2,603,709 twenty-foot equivalent units (TEUs) in August, the third-highest monthly volume on record, as shippers moved more cargo through major gateways despite growing uncertainty over tariffs, Middle East shipping disruptions and new Panama Canal capacity constraints.
Imports rose 3.8% from July and 3.3% from August 2025, Datamyne data. Only May 2022, when imports totaled 2,622,465 TEUs, and July 2025, with 2,621,910 TEUs, produced larger monthly volumes.
The August total was also 21.5% above the pre-pandemic level recorded in August 2019. While cumulative imports through the first eight months of 2026 remained down 0.4% from the same period a year earlier, the August gain narrowed the year-to-date deficit and pointed to resilient late-summer import demand.
Port volumes broaden across regions
The nation’s 10 largest container gateways handled 84.6% of U.S. containerized imports in August and collectively increased volume by 80,661 TEUs, or 3.8%, from July. Eight of the 10 ports posted monthly gains.
New York/Newark recorded the largest increase, up 24,122 TEUs, or 7.2%, from July. Savannah followed with a gain of 22,761 TEUs, or 9.2%, while Long Beach increased by 12,945 TEUs, or 2.8%.
In the Gulf region, Houston posted an 8,569-TEU increase, up 4.7%. New York-New Jersey gained 8,548 TEUs, or 18.1%. Charleston rose 5,751 TEUs, Tacoma increased 4,829 TEUs and Norfolk added 511 TEUs.
Delays rise at every major gateway
Stronger throughput was accompanied by higher transit delays across all 10 major ports, report.
Houston and Seattle registered the biggest increases. Houston’s average delay rose 1.5 days, from 4.3 days to 5.8 days, while Seattle increased by the same amount, from 6.1 days to 7.6 days. Savannah’s delay rose 1.3 days to 6.1 days.
Los Angeles, Norfolk, New York-New Jersey, Tacoma, Oakland, Charleston and Long Beach also posted more moderate delay increases. Descartes defines port transit delay as the difference between the estimated arrival date initially listed on a bill of lading and the date on which it receives U.S. Customs and Border Protection-processed bill-of-lading data.
Gulf Coast momentum continues
Gulf Coast ports continued to gain volume in August, handling 252,675 TEUs, a 4.2% increase from July.
The August total was 11.7% above the Gulf Coast’s rolling 12-month average of 226,120 TEUs and was only 1.9% below the region’s 2026 high of 257,564 TEUs set in May. August represented the second-highest total in the period covered by the report and extended a rebound that began in July.
China imports rise, but share slips
U.S. imports from China totaled 884,318 TEUs in August, up 1.3% from July and 1.7% from August 2025. Still, China-origin imports remained 13.5% below the record 1,022,913 TEUs handled in July 2024. China accounted for 34% of all U.S. containerized imports in August, down from 34.8% in July.
Plastics, and furniture and bedding remained the largest product categories in China-origin imports, representing 14% and 13.3% of the total, respectively. Machinery and electrical machinery combined for 17.6%, while toys and sporting goods accounted for 9.9%. Apparel, made-up textiles and footwear collectively represented 10.7% of August China-origin import volume.
Sourcing growth extends beyond China
The report found import growth was broadly distributed across leading supplier countries.
The top 10 countries of origin collectively increased U.S.-bound container volume by 61,735 TEUs, or 3.5%, from July. Vietnam recorded the largest month-over-month gain, rising 14,545 TEUs, or 5.2%. Thailand increased 11,633 TEUs, or 10.4%, while Indonesia rose 11,198 TEUs, or 19.5%.
China added 11,188 TEUs from July. Germany increased by 5,195 TEUs, South Korea by 4,303 TEUs and Hong Kong by 2,222 TEUs. India was the only top-10 sourcing country to decline, falling 926 TEUs, or 0.8%.
Trade risks cloud outlook
The August import surge occurred against a backdrop of rising supply-chain uncertainty.
Operational conditions around the Strait of Hormuz remained volatile at the end of August. Booking suspensions and reduced operations in parts of the Uphave required some carriers and cargo interests to consider alternative land-bridge routings, temporary storage arrangements and specialized empty-container return procedures.
Tariff policy also remains a material landed-cost consideration. Section 301 tariffs introduced July 24 apply additional duties across numerous trading partners, generally ranging from 10% to 12.5%, although rates, exemptions and caps differ by country and product. Existing Section 232 duties and China-related Section 301 measures add to the need for importers to assess duty exposure at the individual Harmonized System code level.
Source: FreightWaves
Compiled from international media by the SCI.AI editorial team.